Budgeting & Money Habits
First car, first winter: what young and first-time buyers should know before signing
October 26, 2026 · 7 min read
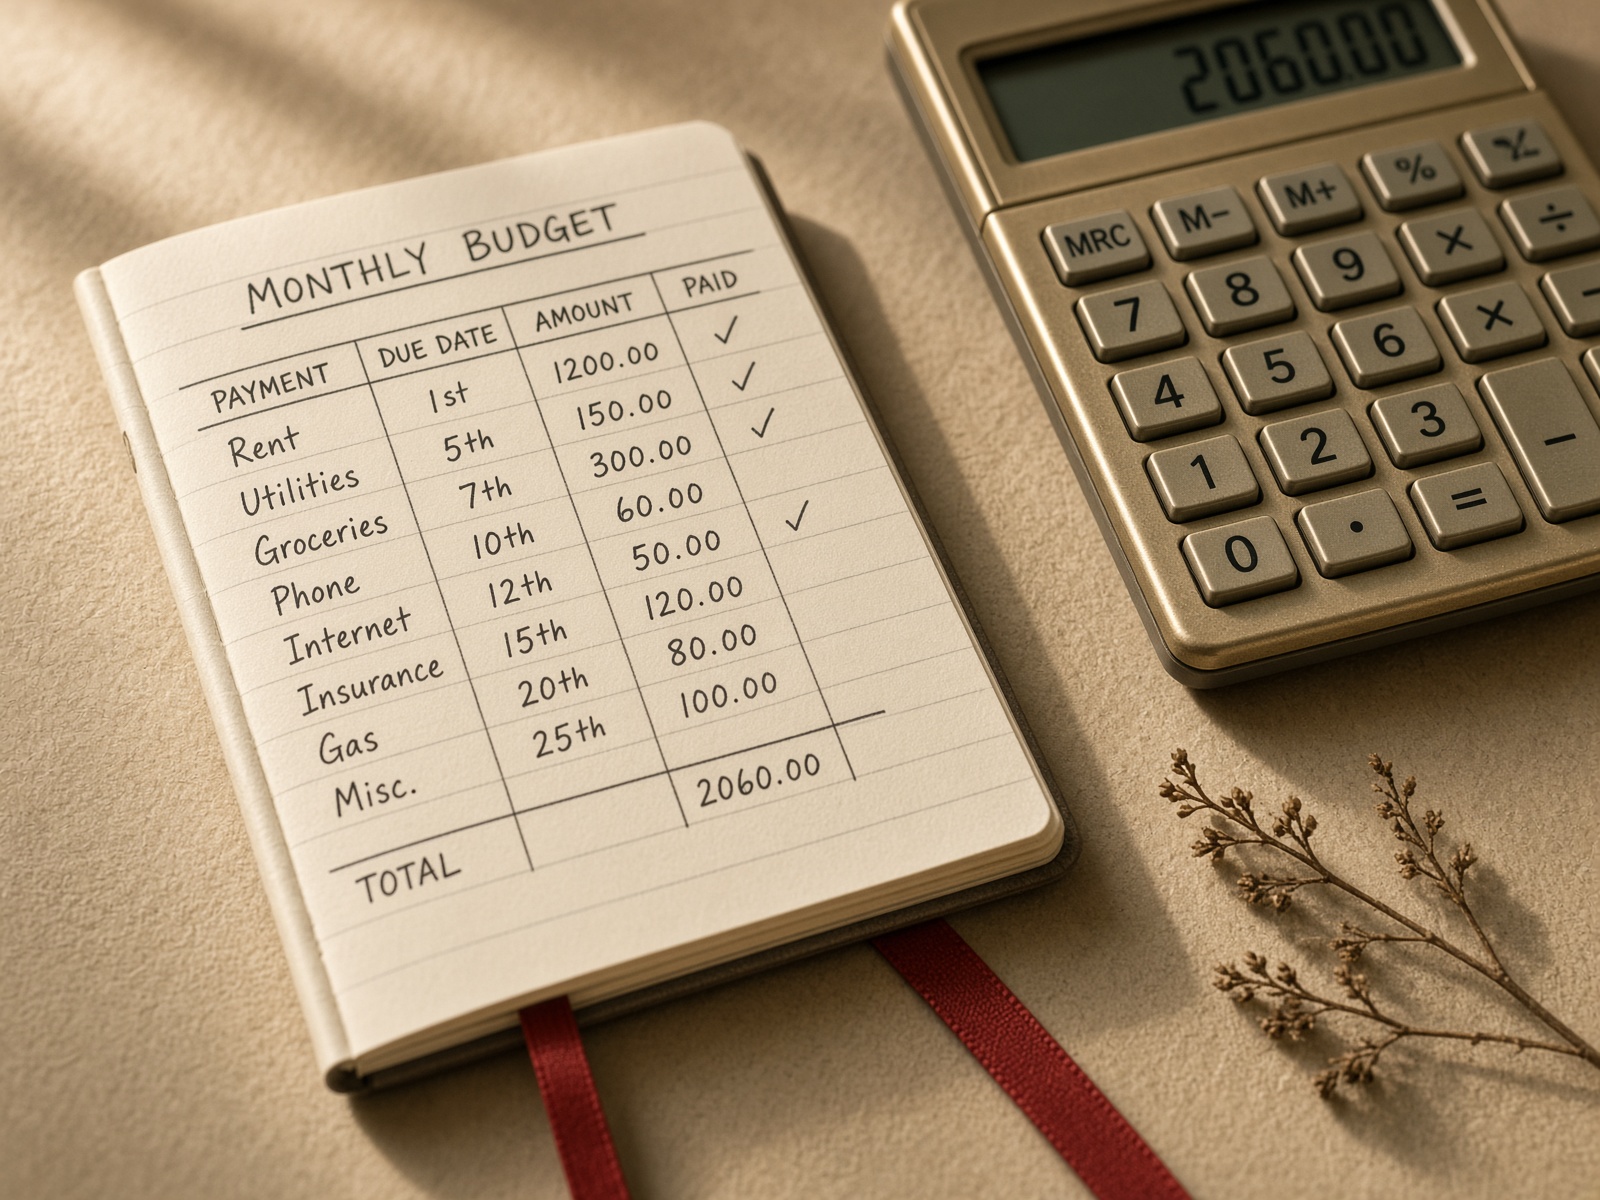
A first car loan usually arrives alongside a lot of other firsts: a first full-time job, a first apartment, maybe a first Ontario winter as the driver instead of the passenger. That is a lot of new numbers at once. None of them are a test of whether you are responsible. They are just numbers, and they get easier when you see them in order.
This is educational, not a promise of approval or a particular rate. Every file is different. I work as a Finance Manager at Frontier Fine Cars. Education lives here. The contract, if there is one, is completed in person at the registered dealership.
1. A thin credit file is a starting point, not a verdict
If you have one credit card, a phone plan, and maybe a student line of credit, lenders have a short story to read. That is normal for a first-time buyer. What helps most is boring: paying everything on time, keeping card balances low compared with the limit, and not opening new accounts in the weeks before you apply.
If you are not sure what your file looks like, you can request your credit reports from Equifax Canada and TransUnion Canada. Checking your own report does not lower your score, and it is the easiest way to catch a mistake before a lender does.
2. Five dealerships in one weekend: did that hurt your rate?
It is one of the most common questions I get. Shopping around feels responsible, and comparing can be. But a full credit application is a hard inquiry. Scoring models often group auto-loan inquiries made in a short window — but not always, and not when they are mixed with other credit applications. On a thin file, a cluster of inquiries can stand out more than it would on a long one.
The calmer approach: pre-qualify once, ask whether the check is a soft inquiry or a full application, and learn your realistic payment range before you visit lots. Then you are comparing vehicles inside a budget instead of sending your file to every lender in town.
3. The co-signer conversation, honestly
A parent, guardian, or partner with a longer file can make a first loan more realistic. But a co-signer is fully responsible for the loan — not a reference. If a payment is missed, it can show on both credit reports. Have that conversation at the kitchen table, with the real monthly number, before anyone comes to the dealership. The co-signer guide on this site walks through the full picture.
4. Your first winter with a car payment
Winter is when the costs beside the payment show up. Budget for them before you sign, not after the first cold snap: winter tires and rims, plus storage or a seasonal swap if you do not have space; insurance, which for young drivers is often the biggest number after the payment itself; a battery that is not new, wiper blades, washer fluid, and a scraper; higher fuel use on cold mornings; and a small emergency buffer for the tow or repair nobody plans.
If the payment only works when nothing else goes wrong, it is not the right payment yet. A payment you can keep in February matters more than one that looks good in October.
Already financed your first car and wondering how long to wait before trading it in? Early in a loan, many cars are worth less than what is still owed. Before you shop for the next one, use the free Trade-In Equity Check to see if you have negative equity — and how big the gap is.
5. A first-time buyer sequence that keeps you in control
1. Check your own credit reports and fix anything that looks wrong. Write down your take-home pay and your real monthly costs, including rent, phone, and transit you will still use.
2. Get an insurance quote on the type of vehicle you are considering. Young-driver premiums can change the whole budget, so this comes before shopping, not after.
3. Pre-qualify once. Ask whether it is a soft check, and ask what documents you will need — usually ID and proof of income, plus the same for a co-signer if there is one.
4. Decide on a co-signer before the appointment, not during it. If the answer is yes, bring them with you. If the answer is not yet, that is a fine answer too.
5. Choose the vehicle inside the range, in person, at the dealership, where it can be inspected and the contract can be read slowly. Ask about term, rate, total cost, and what happens if a payment is late.
Nothing on this page is a promise of approval or a particular rate, and this site does not list vehicles. If you want to walk through a first loan — on your own or with a co-signer — pre-qualify through Rhanda’s intake, read the other guides here, or visit Frontier Fine Cars, 1261 Kennedy Rd, Unit A, Toronto, and ask for Rhanda. Where your finance meets real care.